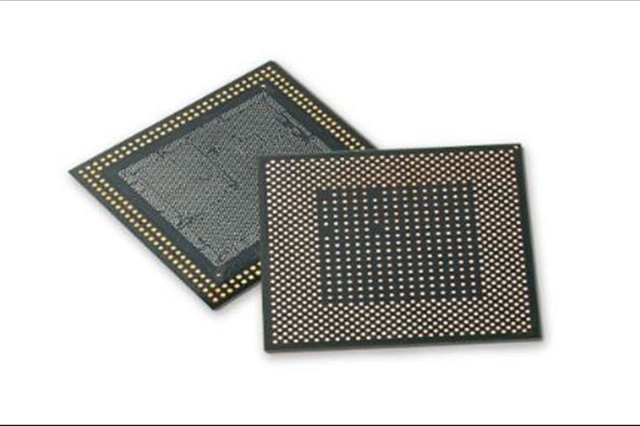
Samsung Electro-Mechanics is investing KRW6.78 trillion (approx. US$5 billion) to expand FCBGA capacity in South Korea and Vietnam. The projects are backed by customer funding and medium- to long-term volume commitments, as demand for high-performance package substrates pushes Korean production lines toward high utilization.
The expansion comes as South Korea's PCB industry shifts toward higher-value products rather than simply shipping more boards. Korea Customs Service data cited by The Korea Economic Daily show PCB exports reached US$3.563 billion in the first eight months of 2026, up 14.4% from a year earlier, while export volume increased just 1.8% to 11,411 metric tons from 11,206 tons. Hankyung expects full-year exports to challenge the 2022 record of US$5.9 billion.
The gap between value and volume reflects a richer product mix and higher substrate prices. Demand is increasingly concentrated in advanced package substrates such as FCBGA, which are used with server CPUs, GPUs and accelerators, as well as in high-layer-count multilayer boards used in data center systems.
High-end substrate lines run near capacity
Samsung Electro-Mechanics' semiconductor substrate lines averaged 89% utilization in the first half of 2026, up from 70% in 2025. LG Innotek's Gumi substrate lines reached 94%, compared with 80.8% last year.
Samsung Electro-Mechanics has benefited from stronger shipments of FCBGA for server CPUs and accelerators, while new products for North American data center networking customers began ramping during the second quarter. LG Innotek's package substrate portfolio spans FC-CSP and RF-SiP, with FC-CSP demand also expanding into memory applications.
The elevated utilization rates leave less spare capacity to absorb additional demand without productivity improvements or new investment.
Broader substrate supply conditions are also tight. Market research firm TrendForce said ABF substrate lead times reached 48–56 weeks in September, compared with around 12 weeks in a balanced market, marking the widest gap among the six infrastructure components it tracks. ABF is a build-up dielectric material widely used in advanced package substrates and should not be treated as interchangeable with FCBGA.
Customers help fund Samsung Electro-Mechanics' largest single-product investment
Samsung Electro-Mechanics will invest KRW4.27 trillion at its Sejong site in South Korea and about KRW2.51 trillion at its Vietnam subsidiary.
The Sejong project is the company's largest investment in a single product. Spending will run from September 2026 through May 2028, with mass production scheduled to begin in September 2028. The Vietnam expansion is targeted to be completed and begin operating in June 2030.
More significant than the scale of the investment is its commercial structure. Global customers are providing investment funding and committing medium- to long-term volumes, reducing Samsung Electro-Mechanics' exposure to the capital costs of adding capacity while providing greater visibility into future utilization.
The company has not identified the customers or disclosed how much of the investment they will finance.
The arrangement gives Samsung Electro-Mechanics greater demand visibility as package substrates become larger, add more layers and grow more complex. Its FCBGA portfolio already includes large-body products for high-performance computing, in which substrates can reach roughly 110mm by 110mm and 26 layers.
LG Innotek pushes further into high-end FCBGA
LG Innotek is also moving further up the package-substrate value chain. The company unveiled an FCBGA designed for accelerators at KPCA Show 2026 in September. The substrate measures more than 100mm on each side and is roughly six times the size of its PC FCBGA sample.
Mass production of high-value FCBGA for training and inference applications is targeted for 2027, while glass-core substrates are scheduled to enter mass production in 2028.
The product shift is already visible in earnings. LG Innotek's Package Solution business generated KRW935.6 billion in first-half revenue, up 18% from a year earlier, while operating profit rose 94% to KRW99.6 billion. Operating margin improved to 10.6% from 6.5%.
The company is also expanding package-substrate production geographically. Its Haiphong investment in Vietnam is intended to add semiconductor substrate capacity alongside its existing Gumi operations, with the new facility scheduled for completion in May 2027.
Expansion spreads to mid-sized suppliers
The capacity cycle is extending beyond Korea's two largest substrate suppliers.
Daeduck Electronics is increasing its exposure to FCBGA, FC-CSP and server-related multilayer boards. Its second-quarter revenue rose 63.1% from a year earlier to KRW401 billion, while operating profit reached KRW70.3 billion and operating margin climbed to 17.5%. Higher sales of memory and non-memory package substrates, together with a richer product mix, supported the improvement.
Daishin Securities expects Daeduck's FCBGA revenue to rise from KRW221.1 billion in 2025 to KRW374.8 billion in 2026 and KRW473.3 billion in 2027, lifting FCBGA's share of total revenue from 20.8% to 26.7% over the period.
Daeduck plans to invest KRW510 billion through the end of 2027, with much of the spending directed toward FC-CSP and FCBGA capacity. Demand for FC-CSP is expected to broaden beyond mobile processors into GDDR and LPDDR5 products used in inference servers, as well as storage controllers.
Elsewhere, Simmtech is investing KRW400 billion to expand its Cheongju operation, including dedicated PCB capacity for SOCAMM memory modules, while Isu Petasys is increasing its exposure to multilayer boards for accelerators.
Value replaces volume as the growth driver
The current cycle looks different from the industry's 2022 peak, when smartphones, PCs and other traditional electronics were major growth drivers.
This time, Korean PCB export tonnage is nearly flat while export value is growing at a double-digit pace. Major substrate lines are operating at close to 90% utilization or higher, and investment is increasingly directed toward larger, higher-layer-count and more technically demanding products.
Capacity timing could also remain important for buyers. LG Innotek is targeting its next high-end FCBGA ramp in 2027, Daeduck's current investment program runs through the end of that year, and Samsung Electro-Mechanics' major new Sejong capacity is not scheduled to begin production until September 2028.
Article edited by Jerry Chen