
AI-driven enterprise procurement and a consumer shift toward higher-end products lifted Synnex Technology International's revenue and profit in the second quarter of 2026, with profit growing far faster than revenue, showing that volume growth is increasingly translating into stronger profitability.
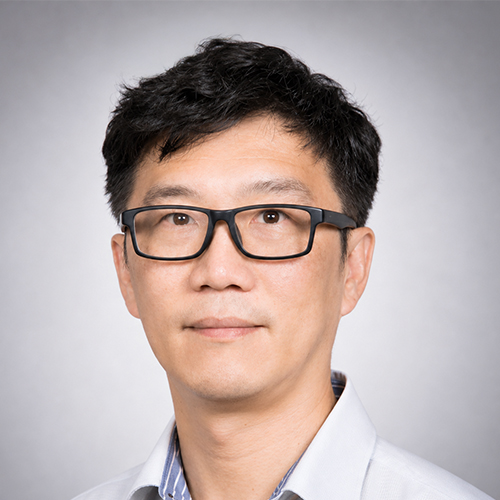
Looking ahead, Vice President and spokesperson Shu-Chyuan Tu said that as AI applications move from pilot validation to large-scale deployment, enterprise IT infrastructure and data center upgrades have shifted from a discussion point to a productivity necessity. With the traditional second-half peak season and product launches such as new Apple devices and Nvidia's next-generation graphics cards, value-added commercial products and semiconductors will remain the primary growth engines throughout the next two quarters. This momentum is expected to extend into 2027.
By product line, even though mobile phone shipments declined, revenue still grew around 45% in the second quarter thanks to a portfolio shift toward mid- to high-end models. Revenue in July rose more than 18% year-over-year. Gaming products grew about 7%, and wearables and other consumer electronics posted double-digit growth. Household consumer electronics revenue saw a 30% year-over-year increase in July.
Semiconductor sales remained the biggest highlight, driven by higher prices for DRAM, hard drives, and other storage products, as well as imbalances in supply and demand. The company saw strong growth in the second quarter and the first half of 2026, with July revenue up about 150% year-over-year. CPU and platform IC revenue also maintained moderate growth of 20% to 30%.
Tu pointed out that Synnex uses its in-house MSP digital intelligence platform to track supply chain shortages, helping the company win new business beyond existing customers. Enterprise and cloud-based commercial value-added businesses were robust as well, with July revenue up about 200% year-over-year, making it one of the fastest-growing categories recently.
In regional markets, China and Taiwan were the strongest performers in the second quarter. China's growth was driven mainly by a roughly threefold expansion of its commercial market, which Tu linked to local government efforts to localize IT equipment and speed up the implementation of the "xinchuang" (information technology application innovation) policy.
Synnex has seen notable gains with core brands including Huawei, Inspur, and Tsinghua Tongfang, as well as newer vendors such as Henan Kunlun, Huakun Zhenyu, and xFusion. In Taiwan, the commercial market was the main driver, with consumer and mobile businesses both growing more than 20%.
Although the Australian and New Zealand markets were smaller, they continued to grow steadily. Indonesia maintained growth in the 20% range for the full year; mobile revenue in Indonesia jumped 72% on a sharp increase in retail prices. Hong Kong, by contrast, saw revenue flatten in the first half of the year after mobile sales fell more than 50%, although revenue returned to positive growth in July.
On profitability, the operating expense ratio fell to 1.02% in the second quarter and 1.25% in the first half, helping lift the first-half operating margin to nearly 2.5%. Even though gross margin declined due to an increase in larger projects, overall profitability was not affected.
Tu explained that some recent projects are worth tens of billions of New Taiwan dollars. Although gross margins are only about 5% to 6%, the associated expenses are relatively low. Business decisions are therefore not based on gross margins alone, but on real growth in operating profit and earnings per share (EPS).
During the investor conference, Tu stressed that the current round of price increases for components and end products is not a short-term windfall. "Once prices go up, it is actually not easy for them to come down," he said, adding that AI-enabled functions and benefits have raised the value baseline across the entire market, and that even if some corrections do come later, the long-term pricing trend will not reverse.
He also said the AI wave is spreading from cloud service providers to midstream and downstream players, and that expansion by OEMs and ODMs in AI servers will directly drive additional semiconductor demand. By integrating suppliers and channel partners through its MSP digital intelligence platform and AI application acceleration platform, Synnex said it expects to continue benefiting from this structural growth and is "very confident" about the outlook.
Synnex reported consolidated revenue of NT$201 billion (approx. US$6.2 billion) in the second quarter of 2026, up 115% year-over-year, with net profit of NT$3.9 billion (US$120.8 million), up 197%, and EPS of NT$2.34. For 1H26, revenue reached NT$327.4 billion (US$10.1 billion), up 77%, while EPS was NT$4.12. Operating income was about NT$8 billion (US$247.9 million), nearly matching the NT$8.6 billion (US$266.5 million) recorded for fiscal 2025, and return on equity reached 19%.
Additionally, consolidated revenue for July 2026 came to NT$72.3 billion (US$2.2 billion), up 127% year-over-year. Revenue for January to July 2026 totaled NT$399.7 billion (US$12.4 billion), up 85%, and was already equivalent to about 97% of fiscal 2025 revenue, leaving a gap of only about NT$11.5 billion (US$356.3 million) compared with the full-year figure.
Article translated by Yunnie Cheng and edited by Ysi Chen