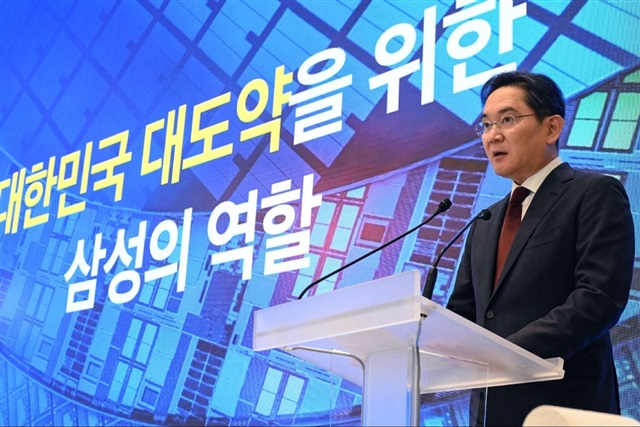
Five senior Samsung Electronics executives, including the heads of its semiconductor and consumer electronics businesses, reportedly traveled to Tokyo on October 13 while chairman Lee Jae-yong was visiting Japan, bringing together the company's three executive directors and key corporate decision-makers as it expands cooperation with Japanese semiconductor suppliers.
Taiwan Mask Corporation (TMC) is expanding its presence in Japan through the acquisition of semiconductor equipment services provider TCK, extending its business beyond precision photomask manufacturing to equipment assembly and engineering support in Japan's growing Kyushu semiconductor market.
Chinese EV giant and AI mobility manufacturer XPeng has made a major appearance at the Paris Automotive Summit by bringing not just its automotive expertise into the European collaborative space, but a broader technology stack built on the automaker's existing strengths in EV manufacturing and humanoid robotics.
Samsung Electro-Mechanics (Semco) faces potential equipment procurement bottlenecks in its KRW6.78 trillion (approx. US$5.1 billion) expansion of semiconductor substrate production for AI servers, as machinery manufacturers struggle with component shortages and longer delivery times. The South Korean company maintains that its investment is proceeding as planned. No production delay has been confirmed.
FICG is aggressively expanding optical communications production in Malaysia and China to meet surging AI-driven demand, which the company estimates is 3-4x current supply capacity. Chairman Leo Chien described the next three years as a "frenzied expansion period," with the company's Johor, Malaysia, facility set to increase capacity 4x by the end of 2027.
Chinese automakers are accelerating their expansion into humanoid robotics, leveraging artificial intelligence (AI) technologies, electric drive systems, and supply chain resources developed through their automotive businesses, according to DIGITIMES Intelligence.
China's semiconductor and computing hardware companies reported or forecast strong earnings growth in the first nine months of 2026, fueled by AI infrastructure investment, demand for domestic processors and optical interconnects, and recovering chip markets. However, diverging quarterly results reveal a widening gap between AI-driven growth and the traditional memory pricing cycle.
Japan is stepping up its push into physical AI, with major technology companies and research institutions showcasing advances in autonomous robot learning, motion sensing, and agricultural automation at CEATEC 2026.
LG Innotek expects to begin supplying glass substrates for advanced semiconductor packaging around 2028 and sees its chip substrate business improving in 2027, as the South Korean components maker seeks to reduce its reliance on smartphone camera modules and expand into automotive technologies.
Japan's automakers are presenting autonomous-driving systems that connect vehicles with road infrastructure as a route toward deployment, highlighting a strategic choice beyond vehicle-only artificial intelligence. At Japan Mobility Show Bizweek 2026, Nissan, Subaru, and Toyota are demonstrating technologies that combine onboard systems, cloud data, sensors, and communications to improve safety.
China's largest chip equipment makers are buying their way into hybrid bonding, the advanced packaging step that global players from Besi to ASML are also chasing. For Chinese firms, analysts say, the stakes are different: with US export controls limiting access to the tools needed for leading-edge transistor scaling, stacking and connecting chips more densely has become one of the few routes left to narrow the performance gap, an approach Huawei has framed as its Tau scaling law.
As interest rates fluctuate, bond yields rise, and Chinese AI models intensify competition, market attention is shifting from technological development and infrastructure expansion to investment returns and long-term debt-servicing capacity. The AI industry continues to attract capital but must also prove that its business models can generate profits.
As artificial intelligence increasingly blurs the boundary between the digital and physical worlds, complications associated with real-world deployment — particularly the extreme variability of physical environments — are emerging as a subtler configuration challenge in the industry spotlight.
As Manus, one of China's more distinctive AI startups, became entangled in the high-profile unwinding of its acquisition by Meta, the startup's failed attempt to capture opportunities beyond China left the industry speculating about its next steps after an abrupt regulatory reversal.
China's Yangtze Memory Technologies (YMTC) is developing a next-generation 4F² DRAM design targeting data transfer speeds of 9,600 megatransfers per second (MT/s), expanding beyond NAND flash as the company pursues a CNY33 billion (approx. US$4.93 billion) Shanghai initial public offering.
South Korea's LG Innotek expects its semiconductor substrate business to improve in 2027 as it pursues long-term supply agreements (LTAs) with major technology companies and prepares to enter the high-end AI accelerator market. Under this strategy, the company aims to secure customer commitments before expanding production capacity as it seeks to diversify beyond smartphone camera modules.