CONNECT WITH US
Sep 18
Foldable smartphone panel shipments fall 13% in 1H26 as market shifts to in-fold designs
Global foldable smartphone panel shipments declined 13% year-over-year in the first half of 2026, with the contraction concentrated in clamshell products, according to Counterpoint Research's Quarterly Foldable Display Shipment and Technology Report.

China's PC monitor market is entering a period of sharper structural divergence, with commercial demand offsetting part of a weakening consumer segment while rising component costs push manufacturers toward higher-value products.

Samsung Electronics will reportedly slash quantum-dot (QD) LCD TV production in 2026 to 2 million to 3 million units, down as much as 80% year-over-year, while it also plans to gradually scale back Neo QLED output and potentially stop production as early as 2028. The move shifts the company's LCD TV focus toward Mini LED models without QD.

Suppliers in China's AR glasses supply chain see the approximately 2 billion people worldwide with myopia as a potential market and said shipments are set to double year after year, even as the industry continues to sift winners from losers. At this year's China International Optoelectronic Exposition (CIOE), smart glasses remained a standout theme alongside optical communications.

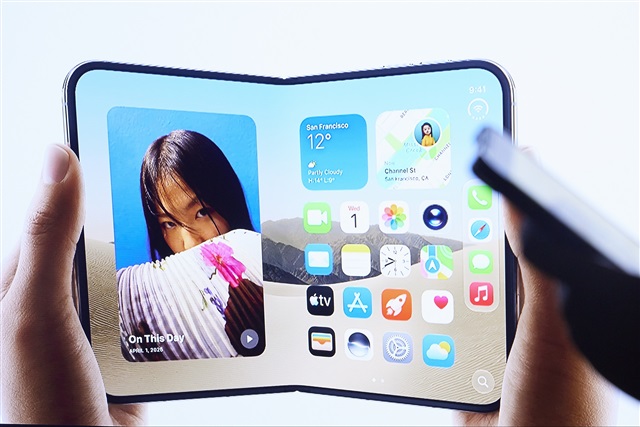
Samsung Display could emerge as one of the biggest supply-chain beneficiaries of Apple's entry into foldable smartphones, as the Korean panel maker already accounts for about two-thirds of global foldable smartphone panel shipments, with Apple set to become a major new source of demand.
Last week, from September 9 to 11, thousands of vendors gathered for an enormous trade show in the Chinese tech hub of Shenzhen. At the China International Optoelectronic Expo (CIOE), DIGITIMES reporters got a peek into the trends going on within this booming industry.
South Korean panel makers command about 80% of the automotive OLED market, according to Sigmaintell, as electrification and smarter vehicles keep demand for car displays stable and drive growth in new applications such as head-up displays. Competition is set to intensify as China's LCD makers press into higher-end automotive screens.

S&P Global Mobility senior research analyst for connected cars and user experience in Asia-Pacific Quan Zhang shared the latest forecasts for the cockpit display and head-up display (HUD) markets.
The 2026 China International Optoelectronic Exposition (CIOE) closed on September 11. While near-eye display applications such as AR/VR and smart glasses drew attention, vendors' latest moves in optical communications also attracted strong industry interest.
Following the launch of Apple's first foldable iPhone, the iPhone Duo, combined sales momentum from Samsung Electronics, Huawei Technologies, Xiaomi, Oppo, Vivo, and Motorola is expected to drive global foldable smartphone shipments above 27 million units in 2026.
China's OLED supply push is gathering pace, with BOE Technology Group (BOE), TCL China Star Optoelectronic Technology and Visionox rapidly expanding production and closing in on South Korean rivals. South Korean companies still hold an edge in OLED for smartphones and TVs, but their room to grow in IT devices and automotive OLEDs is likely to narrow.
CoreIntelligence Holdings (CiHC) reported unaudited consolidated revenue of NT$3.429 billion (approx. US$108.6 million) for August 2026, representing a slight 3% month-over-month decline from NT$3.535 billion (US$112.1 million) in July, but a 3% year-over-year increase compared to NT$3.342 billion (US$105.8 million) in 2025. Cumulative consolidated revenue for the first eight months of 2026 reached NT$26.36 billion (US$834.8 million), up 6% from NT$24.819 billion (US$786 million) recorded during the same period in 2025.