The 2026 China International Optoelectronic Exposition (CIOE) closed on September 11. While near-eye display applications such as AR/VR and smart glasses drew attention, vendors' latest moves in optical communications also attracted strong industry interest.
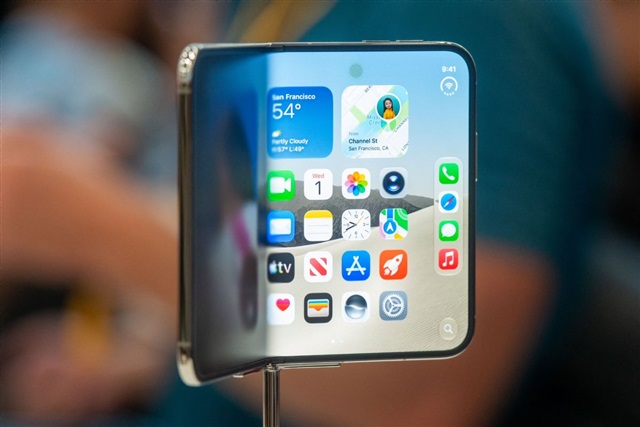
Following the launch of Apple's first foldable iPhone, the iPhone Duo, combined sales momentum from Samsung Electronics, Huawei Technologies, Xiaomi, Oppo, Vivo, and Motorola is expected to drive global foldable smartphone shipments above 27 million units in 2026.
CoreIntelligence Holdings (CiHC) reported unaudited consolidated revenue of NT$3.429 billion (approx. US$108.6 million) for August 2026, representing a slight 3% month-over-month decline from NT$3.535 billion (US$112.1 million) in July, but a 3% year-over-year increase compared to NT$3.342 billion (US$105.8 million) in 2025. Cumulative consolidated revenue for the first eight months of 2026 reached NT$26.36 billion (US$834.8 million), up 6% from NT$24.819 billion (US$786 million) recorded during the same period in 2025.
HannStar Display is preparing to cut output at its only fab roughly in half, alongside a workforce reduction that industry sources put at as much as 70% — being carried out through a voluntary buyout program. The moves landed in the same week its general manager resigned, turning long-running speculation about a plant closure into the central question around the company.
Taiwan's panel makers posted mixed August results as the industry's strategic focus shifts beyond monthly revenue toward AI, advanced packaging and co-packaged optics (CPO). AUO and Innolux, the island's two largest panel makers, are accelerating capacity reductions and asset sales while redirecting capital and technology toward higher-growth businesses. For smaller and mid-sized players, however, the path beyond displays remains far less defined.
Touch panel makers TPK and General Interface Solution Holding reported diverging August revenue trends, but both remained cautious on consumer electronics demand in the second half of 2026. They expect touch and display demand to stay relatively soft.
Samsung Electronics has begun developing its first smart glasses with an in-lens display, asking Samsung Display in August to develop a microdisplay that meets requirements for form factor, display area, color and price, according to industry sources cited by TheElec.
Shenzhen Huachuang Xinguang says MicroLED optical interconnect technology is feasible and expects to target data center applications within 3–5 years.
Economies of scale occur when a company's average cost per unit falls as overall production volume increases. In the competitive display industry, reaching this state relies on either mass production, technological innovation, or specialization. Currently, South Korean and Chinese display manufacturers are pursuing distinct strategies to achieve cost advantages in the OLED market. While South Korea focuses on advanced process integration and technological upgrades, China leverages massive production infrastructure and upcoming facility amortization.
AUO is accelerating its transformation by extending its established large-format panel manufacturing capabilities into advanced semiconductor packaging.
Himax Technologies this week announced an industry-leading automotive touch and display driver integration chip (TDDI) that supports a high-speed eDP interface, combining eDP, touch sensing and display driving on a single chip to meet new-generation smart cockpit demand for large, high-resolution, high-quality displays and real-time touch.
More coverage