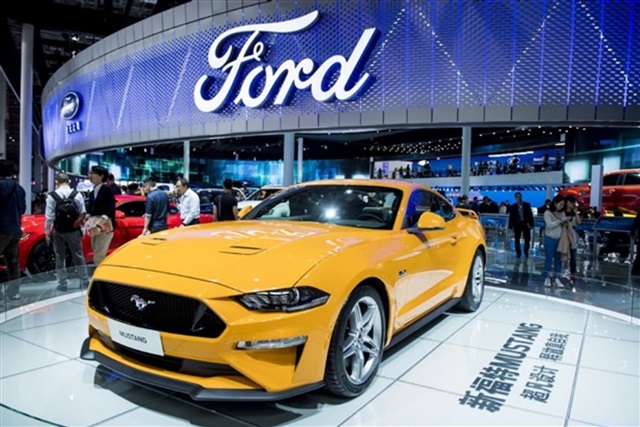
The opening of the North American International Auto Show in Detroit this year offered a revealing portrait of an industry caught at the intersection of political crosscurrents and technological transition—and increasingly at risk of losing its strategic focus. The concern, executives say, is no longer confined to fluctuations in production or sales, but points to something more fundamental: a strategic retreat that could undermine America's industrial sovereignty and long-term competitiveness.
A disordered strategic rhythm
Several supply-chain executives described the current moment as resembling a lament composed to a "disordered strategic rhythm."
At the heart of the problem lies the sharp policy reversals that followed the change of administration in Washington. Long-standing industrial road maps have been effectively scrapped and rewritten, plunging automakers into uncertainty. Detroit's Big Three—General Motors, Ford, and Stellantis—have been hit hardest. While European, Japanese, and South Korean manufacturers, as well as Tesla, are not immune, the most acute disruptions are being felt by US-based carmakers.
John Bozzella, the president and chief executive of the Alliance for Automotive Innovation, told US media that the automotive industry's development cycle—from design and research to mass production—typically extends well beyond a single presidential term. When policies are reset wholesale with each political transition, carefully sequenced industrial plans are inevitably thrown off course.
US$25 billion in write-downs
The most immediate shock, executives say, has come from abrupt shifts in policy direction. The federal government has pulled back from aggressively promoting electric vehicles, while easing emissions standards for internal combustion engine cars. Automakers have been forced to recalibrate product strategies and investment plans midstream. The result: Ford and General Motors have recorded asset write-downs of roughly US$19.5 billion and US$6 billion, respectively, tied to electric vehicle investments.
But the cost of these course corrections has not been borne by automakers alone. Each strategic pivot cascades through the supply chain. Suppliers, having invested heavily to align with earlier electrification targets—expanding capacity, building dedicated production lines, and sourcing specialized modules—now find those investments stranded. What were once growth bets have become sunk costs, casualties of a policy vacuum.
Absent from CES, present nowhere
This unease has been visible on the global stage as well. All three Detroit automakers have opted out of CES 2026, signaling that they are preoccupied with damage control and internal restructuring rather than collaborating with the technology sector to articulate a vision for the future of mobility. In doing so, they have, at least temporarily, ceded influence over how that future is defined.
Filling the void are Chinese automakers, many of them shut out of the US market by trade barriers but eager to assert their technological credentials. Despite obstacles, they have expanded their presence at CES, seeking to claim a voice on the global stage.
The ecosystem shift
Beneath these shifts lies a deeper transformation. Competition in the auto industry is no longer about incremental product upgrades, but about entire systems and ecosystems. As Detroit's legacy manufacturers retrench around internal combustion vehicles, chipmakers such as Qualcomm and Nvidia are accelerating the integration of software-defined vehicle platforms with Chinese automakers, effectively aligning with those pushing ahead on next-generation architectures.
In that context, the United States' decision to impose a 100% tariff on Chinese electric vehicles may amount to little more than a temporary bulwark.
The deeper anxiety for Detroit is what comes next. Once political protection recedes, will American automakers be able to compete against rivals that have already rebuilt their technological foundations? Will they slowly wither behind tariff walls, or will they use this politically engineered grace period to carry out a genuine overhaul of their capabilities?
That question remains unanswered.
Ultimately, this elegy reflects a broader imbalance between the swing of the political pendulum and the realities of industrial development. Only by returning to pragmatic policymaking and respecting the natural cadence of industry can American manufacturing hope to regain its footing in a contest that will determine its future place in the global economy.
Article translated by Elaine Chen and edited by Jerry Chen